3rd Quarter 2026 CIO Commentary

Market Observations

Market Summary

  • Q3 2026 was a quarter with significant cross currents in capital markets. The MSCI ACWI Index was up 1.6% overall with technology being by far the largest contributor (6% return). In fact, all of the ACWI return can be explained by just Microsoft (+38%) and NVIDIA (+16%).
  • Energy also had an excellent quarter with the sector up over 15%. Renewed conflict in the Persian Gulf contributed to a 30% increase in the price of oil in the quarter.
  • Outside of tech and energy, the rest of the market as a group produced a slightly negative return. Healthcare and financials did well but many interest rate sensitive equity areas like small cap, real estate and utilities produced negative returns.
  • For hedge funds, preliminary data from HFRI for the Fund of Funds Composite shows an estimated 1.7% loss the quarter.
  • The most notable macro development was in the bond market. The ten-year U.S. Treasury yield increased by over 80 basis points to close at 5.29%, the highest level in roughly 20 years.
  • Inflation continues to exceed the Fed’s long-term targets, resulting in an increase to the Fed Funds target rate of 25 bps, the first hike in three years.

Rising Treasury Yields – Risks and Opportunities

The yield to maturity on the 10-year U.S. Treasury bond is arguably the most important reference rate in global capital markets. We believe there are a variety of factors that have put pressure on U.S. Treasury bonds this year. The charts below highlight some of these issues.

1. Debt to GDP

Total U.S. government debt outstanding is now roughly 100% of GDP, an all-time high except for a brief period at the end of World War II. However, the explicit debt outstanding likely understates the magnitude of the actual liability. If we include a basic estimate of additional liabilities including employee and veteran benefits, Social Security and Medicare the overall ratio of government liabilities to GDP is 442%.
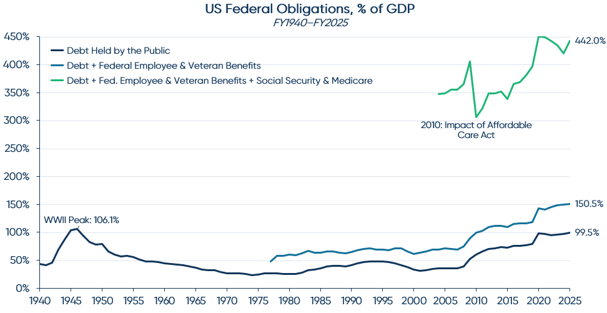
US Federal Obligations, % of GDP
Source: TIFF analysis. OMB Historical Tables (FY2027 Budget), Tables 7.1 and 10.1; U.S. Treasury, Consolidated Financial Statements (1977–1996) and Financial Report of the U.S. Government (1997–2025). Debt held by the public and fiscal year GDP per OMB. Employee and veteran benefits payable per Treasury balance sheet; pre-1997 figures are unaudited and not fully comparable. Social insurance is the 75-year open-group present value (2004–25) and is not a balance-sheet liability.

2. Net Interest Expense as a Percentage of GDP

Total government interest expense as a percentage of GDP is now over 3%, close to the all-time high level from 1991. In addition, the Congressional Budget Office projects that this figure will increase to above 4% over the next decade due to a combination of refinancing maturing debt at higher interest rates, future deficit spending and growing entitlement programs. The reason that the interest expense as a percentage of GDP is so much higher than in the 1940s is because the weighted average rate on the debt outstanding is materially higher (less than 2% in 1945 compared to 3.4% and climbing today).
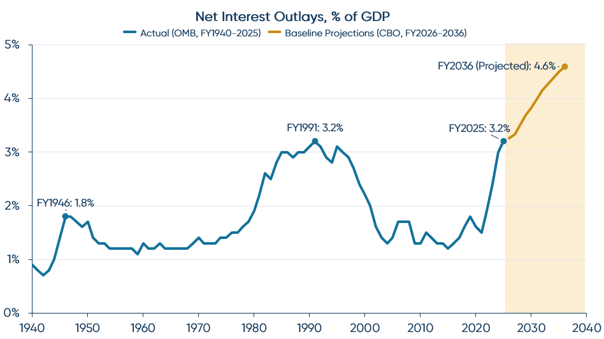
Net Interest Outlays, % of GDP
Source: TIFF analysis. OMB Historical Tables, Budget of the U.S. Government, Table 3.1; CBO, The Budget and Economic Outlook: 2026 to 2036 (Published Feb. 2026), Table 1-1. FY2026–FY2036 are projections.

3. Net Interest Expense / Defense Spending

High interest expenses can crowd out more productive uses of capital including national security, economic growth, public health and other strategically important initiatives. For the first time in U.S. history, the country is now spending more on interest expense than on the military.
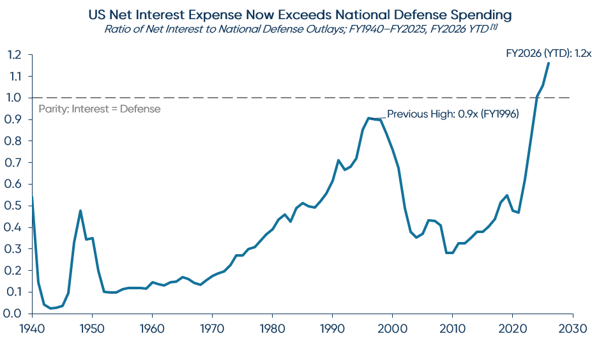
US Net Interest Expense Now Exceeds National Defense Spending
Source: TIFF analysis. OMB Historical Tables, Budget of the U.S. Government, Table 3.1; U.S. Treasury, Monthly Treasury Statement, Table 9. Notes: [1] FY2026 YTD represent published figures from October 2025-August 2026 and will differ from full FY2026 figures once published. U.S. fiscal year runs from October-September each year.
The above set of financial conditions could be improved through adjustments to legislation and balancing the national budget. However, cutting benefit programs or raising taxes tends to be difficult, especially in a highly divisive political environment. In addition, U.S. inflation continues to be at levels higher than the Fed’s long-term targets (implying that the Fed Funds rate is more likely to go up than down). Increased defense spending and adjustments to trade policy could also put upward pressure on costs which have a flow-through impact on inflation and interest rates.

Some readers may argue that many of the above metrics have been challenging for years. Why the move in rates now? That is a difficult question to answer. Technology stocks were at very high valuations for years before the spring of 2000. Major Wall Street investment banks had highly levered balance sheets for years prior to fall of 2008. Identifying the spark that ignites a change in sentiment regarding longstanding risks is hard to do. The U.S. government has gotten away with an unsustainable fiscal imbalance for a long time. Something that can’t go on forever eventually doesn’t. Whether this recent uptick in rates is just noise or the start of a longer-term trend remains to be seen.

In the interest of providing a balanced assessment, there are other reasons why Treasurys have likely been under pressure. Large debt issuance by technology companies to fund the buildout of data centers and other AI infrastructure is also having an impact on rates, particularly in the 5-to-10-year maturity band of the curve. For context, through the last twelve months ending June 30, 2026, just four companies – Alphabet, Amazon, Meta and Oracle – issued close to $300 billion in bonds1. These are businesses that for many years issued very little debt. Between 2020 and 2022, the last years of the pre-AI era, total non-financial U.S. corporate bond issuance averaged less than $1 trillion. While a function of a large move in a short time, current yields are not high relative to long-term history. The best path forward for the U.S. is some combination of continued strong GDP growth and more fiscal discipline, both of which are still possible, but the degrees of freedom and flexibility on timing are starting to tighten.

For our portfolios, the fiscal pressures warrant caution, but higher yields also improve the prospective return from holding Treasurys. Based on an evaluation of the various observations above, we made an adjustment to the bond portfolios outlined in detail in the next section.

Performance, Positioning and Research Priorities

Performance

We expect the liquid portions of our portfolios to exceed the 65/35 benchmark for Q3 by over 1%. Exact totals will vary by client portfolio. In Public Equities, we expect to end up slightly ahead of ACWI. Another strong quarter by our systematic managers was offset by mixed results from some of our fundamental concentrated managers. Diversifiers (mostly hedge funds) had a very good quarter relative to benchmark. The preliminary results for our portfolios are an absolute return of over 1% (with a few accounts coming in lower), over 3% ahead of the HFRI Fund of Funds benchmark. Given the unusually strong performance from funds of hedge funds in the first half of the year, we think there was some reaching for extra return in the asset class. We have not done that, instead choosing to target a consistent risk posture with an expected beta to equities of approximately 0.30, low volatility and a broadly diversified portfolio across complementary sub-strategies. Areas of strong results in Q3 for our Diversifiers portfolio included systematic strategies, merger arbitrage and event-driven equities. Our Fixed Income portfolios generated absolute losses but also generally outperformed their benchmark due to our lower duration in a rising rate environment. We entered the quarter with a weighted average duration of 4.25 years compared to 5.95 years for the Bloomberg Aggregate Index. At this point we have received the private equity marks for Q2. Our private equity portfolios generated a gain of over 4%, a decent absolute result but well behind the MSCI ACWI return of 15% for the comparable quarter. While private investments have underperformed public equities over the past few years, we continue to believe in the long-term prospects for the asset class. Particularly in the two strategies that we manage in-house as opposed to with outside managers – direct transactions with independent sponsors and secondaries – we are continuing to source attractive opportunities.

Positioning

We continue to be close to benchmark across geography and sector exposures within Public Equities. During the quarter, we completed a review of AI-related exposure, which spans multiple industries and may not be fully captured by traditional risk models. Using AI-assisted analysis of public company information, followed by investment team review and comparison with external research, we identified businesses with meaningful AI sensitivity. Overall, we were underweight AI-related businesses broadly, consistent with our underweight semiconductor exposure that detracted from Q2 performance. We used July’s market weakness to selectively increase AI-related exposure through adjustments to passive holdings. These changes shifted the composition of our expected tracking error toward idiosyncratic security selection and away from general factor risk.

In addition, we made an adjustment to our bond portfolios at the end of September. Our bond benchmark is the Bloomberg Aggregate Index. However, our preference is to run conservatively in this area and assume corporate cash flow risk elsewhere in the portfolio, particularly in equities, where we think we will be better compensated over time (i.e., unlimited upside, unlike with investment grade bonds). That is why our portfolios have been almost 100% U.S. Treasury bonds and bills for most of the past decade. In addition, we have had lower duration than the benchmark for years, particularly during the COVID period when we gauged that bonds offered zero real return and diminished diversification value. We have increased duration over the past few years, but have remained underweight the benchmark for a variety of reasons including those noted above. Having lower duration has served us well over 2026 as rates have risen. However, by the end of the quarter Treasury yields had reached 20-year highs and long-term inflation expectations, at least as measured by TIPS breakevens, have remained modest at roughly 2.0.-2.5%, depending on forecast horizon. While there is always a risk that actual inflation will be higher than expected inflation, an implied real return between 2.5% and 3.0% represents some of the best value we have seen in Treasurys in decades. We increased our duration to 5.0 years over last few trading days in September. Similar to the AI adjustment in equities, we are still assuming less duration risk than the benchmark, but it made sense to reduce the size of the bet given the price moves in Q3.

We concluded several manager research initiatives this quarter, adding managers to portfolios where appropriate. In Public Equities, additions included Japanese activist strategies focused on improving corporate capital allocation, a multi-manager platform combining fundamental research with systematic risk management, and two emerging fundamental managers. We funded these investments with redemptions from several other active manager positions. We secured favorable fee terms for clients on several of the additions. Within Diversifiers, we gained access to a capacity-constrained systematic manager we have followed for years. We suspect that the limited distributions from private equity portfolios over the past few years is continuing to cause other investors to be forced to make redemptions from their more liquid positions, creating opportunities for us. Together, these additions reflect our ongoing work to continuously improve the portfolios.

Research Priorities

We have multiple promising manager ideas in process, but they do not fall neatly into a single theme and many are earlier stage than some of the ideas we outlined last quarter. We are in various stages of diligence on a multi-manager platform we have followed for years where a change to their terms has made the investment more attractive to us, several public equity managers in Europe and some systematic and arbitrage managers in Asia, a market that continues to have an attractive combination of good liquidity, high volatility and wide dispersion of returns across stocks – a generally supportive set of conditions for active management.

General Updates

In September, TIFF’s Private Markets team hosted its second annual Capital Connections event, bringing together roughly 100 independent sponsors, institutional investors and our board. The program opened with a closed-door information session for sponsors regarding LP priorities when evaluating a first-time fund, followed by a reception and dinner. The event has already generated follow-up deal flow, strengthening TIFF’s relationships across the independent sponsor community. Events like this are critical to our sourcing of leading independent sponsors and deepening our connection to the private equity ecosystem.

We look forward to seeing many of you in Boston on October 28th and 29th at the 2026 TIFF Investment Forum. Thank you for your ongoing partnership and best wishes for a great close to 2026.


Past performance is no guarantee of future results and the opinions presented cannot be viewed as an indicator of future performance. There is no guarantee that any particular asset allocation or mix of strategies will meet your investment objectives.

These materials are being provided for informational purposes only and constitute neither an offer to sell nor a solicitation of an offer to buy securities. These materials also do not constitute an offer or advertisement of TIFF’s investment advisory services or investment, legal or tax advice. Opinions expressed herein are those of TIFF and are not a recommendation to buy or sell any securities.

These materials may contain forward-looking statements relating to future events. In some cases, you can identify forward-looking statements by terminology such as “may,” “will,” “should,” “expect,” “plan,” “intend,” “anticipate,” “believe,” “estimate,” “predict,” “potential,” or “continue,” the negative of such terms or other comparable terminology. Although TIFF believes the expectations reflected in the forward-looking statements are reasonable, future results cannot be guaranteed.

HFRI Fund of Funds Composite Index is an equal weighted index reporting returns (net of all fees) of participating hedge funds of funds. A fund of funds may allocate its assets to numerous managers within a single strategy, or to numerous managers in multiple strategies. HFRI indices are being used under license from Hedge Fund Research, Inc., which does not approve of or endorse the contents of this report.

Footnotes

  1. Includes a $27.3 billion bond issued in October 2025 by Beignet Investor LLC, a Blue Owl Capital-controlled vehicle financing Meta’s Hyperion data center in Louisiana.
2nd Quarter 2026 CIO Commentary

Market Observations

Market Summary

  • Q2 2026 was a strong quarter for equities, with ACWI rallying 14.9% after a 3.2% decline in Q1 due to concerns about the US-Iran conflict.
  • A combination of a ceasefire in Iran, sustained AI-related earnings momentum, and overall optimism about AI capex spend were key positive drivers.
  • Early data indicates a solid quarter for hedge funds, particularly longer-biased equity long/short funds, many of which likely benefitted from AI-related exposure and possibly private company exposure to SpaceX.
  • It was a weaker quarter for bonds as yields backed up slightly, perhaps due to a combination of reallocations to riskier investments after the Iran ceasefire, persistent inflation, and renewed uncertainty about the path of interest rates over the second half of the year.
  • Beyond these headline results, there are several areas we are monitoring that could create a combination of both risks and opportunities over the remainder of the year.

Concentrated Leadership

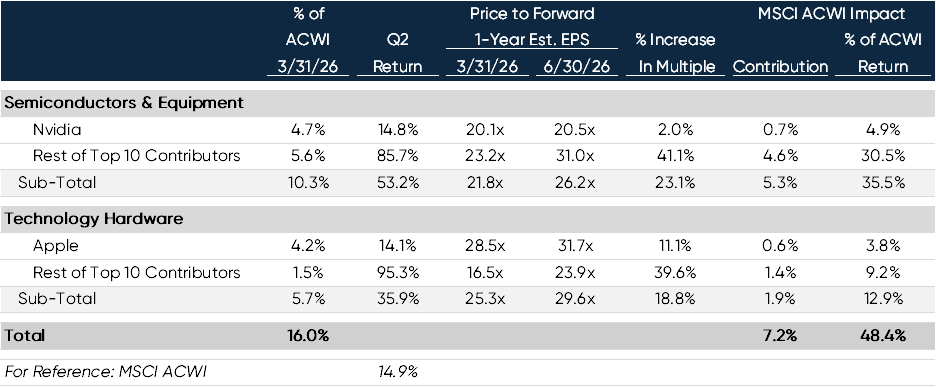
While it was a great quarter for stocks overall, a small number of businesses related to AI hardware capex, specifically semiconductors and memory companies, carried the market. The table below summarizes performance, valuation, and return contribution statistics for just the top ten contributors within the semiconductor and tech hardware industry groups. Bottom line: just 20 stocks in two verticals within tech were responsible for half of the overall index return. Except for Apple and Nvidia, these stocks were up close to 100% on a capital-weighted average basis on the quarter (five of these stocks were up over 200%). As leadership has narrowed, marginal investor demand has become levered. Several asset managers have launched ETFs that hold just one of these stocks on a levered basis. One of these ETFs has grown by over $15 billion in the last six months.

Metrics For Top 10 Contributors in Two Tech Subsectors1

Metrics For Top 10 Contributors in Two Tech Subsectors

Other parts of the AI value chain have not rallied to the same extent. If the appreciation of the high performers proves to be justified by the fundamentals, we would expect these other areas to do well and the market leadership to broaden. However, if the sentiment about AI reverses or fundamentals stall, the top performers from Q2 may have a long way to fall. Some of the recent buyers are levered players, and current valuations are demanding, particularly for the more cyclical companies.

Heavy Forward IPO Calendar

The second market dynamic we are monitoring is the potential impact of several very large IPOs. SpaceX completed its $86 billion offering (including greenshoe) on June 12 and currently trades at a total valuation of over $2 trillion. In addition, the market expects Anthropic and Open AI to complete IPOs over the next few months. The exact sizes of the offerings and company valuations are unclear, but both are expected to raise at least $60 billion dollars and trade at greater than $1 trillion valuations. IPOs of this size are unprecedented. These three mega IPOs are also unusual because the percentage of the total shares sold at the IPO are well below average. Most IPOs are sales of roughly 20% of the total shares. SpaceX sold only 5%.

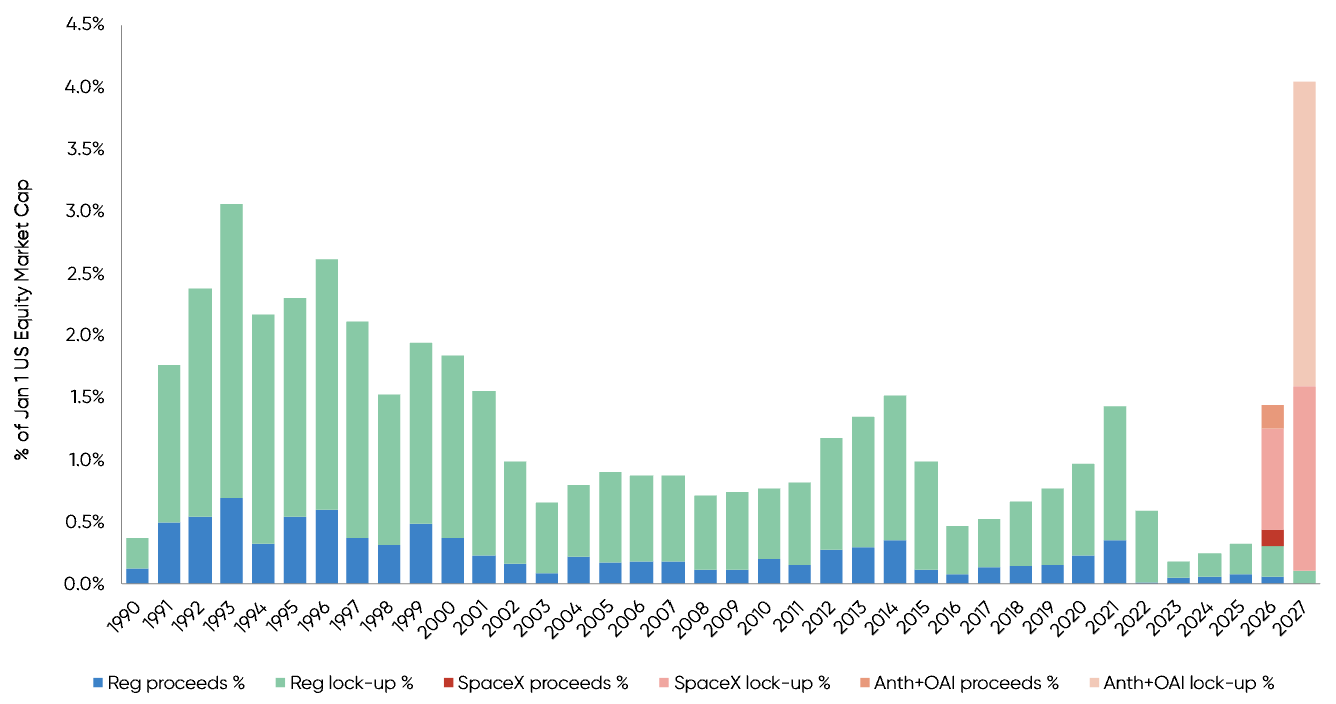
Shares not sold in an IPO are typically restricted from trading for six months after the offering, meaning that for these three mega IPOs, in addition to the very large amount of dollars raised on the IPO dates, there is also an unusually large backlog of subsequent shares that will come off lock-up between six and twelve months later. The chart below summarizes this dynamic.

US IPO Proceeds & Insider Lock-Up Releases as % of Jan 1 Market Cap (1990-2027)2

US IPO Proceeds & Insider Lock-Up Releases as % of Jan 1 Market Cap (1990–2027)

The blue bars represent actual IPO proceeds from the past few decades. The green bars represent shares released from lock-up following those prior IPOs. The red and orange bars represent shares coming to market associated with the “big three” mega IPOs of 2026. Importantly, this analysis likely understates the aggregate value of the supply coming to market for two reasons:

  1. It ignores potential 2026 and 2027 IPO volume from other companies (difficult to predict, though we know that other private companies are considering IPOs).
  2. It assumes that the shares coming off lock-up are valued at the original IPO price.

If the offerings are successful, the actual value of the shares following the lock-up period may be significantly higher. IPO activity over the past few years has been well below average. However, there will need to be significant demand from public investors for the “big three” new offerings over the next year for them to trade well. Absent a big cash infusion in the form of dividends or share buybacks, raising enough cash to buy shares of the “big three” may put downward pressure on other parts of the equity markets.

Long-term Impact of US-Iran Conflict

We are giving a lot of thought to the long-term impact of the US-Iran conflict on oil prices and the energy markets. As for oil prices, they are likely to stay below $100 / barrel over the short term if traffic out of the Strait of Hormuz can return to normal. Longer term, there is a possibility that oil prices will continue to decline or at least be much less impacted by geopolitical conditions in the Persian Gulf. We see parallels to the onset of COVID, when a shock to the system caused multiple market participants to re-evaluate and ultimately restructure their supply chains. Recent events may cause both suppliers and consumers of oil to reassess their supply chains. Exporting nations in the Gulf are likely to explore alternative distribution routes via pipelines that enable them to bypass the Strait entirely for a greater percentage of their total volumes. Increasing pipeline capacity will be costly and time-consuming but may be worthwhile. Similarly, importing countries, particularly in East Asia, are likely to accelerate their efforts to electrify their transportation networks and other infrastructure to reduce their dependency upon a single region for a critical input. These adjustments would be supportive for a combination of electric vehicles, batteries, certain metals, power infrastructure, and construction-related businesses. We also have seen somewhat greater support of exports by formerly sanctioned countries such as Russia, Iran, and Venezuela.

A Co-CIO Conversation: Risks We Are Watching

As we continue working together in TIFF’s Co-CIO structure, we have been focused on which risks are most likely to matter for portfolios in the second half of the year.

Markets have performed well, supported by solid GDP growth, positive employment trends, and easing inflation pressure as oil prices normalize following the Iran conflict. This provides a constructive backdrop for risk assets. At the same time, the questions ahead are becoming more complex: Will the AI buildout put upward pressure on inflation before productivity benefits emerge? Will equity leadership broaden beyond a narrow group of large-cap technology and AI-related companies? Will the expected IPO calendar affect the supply/demand balance for capital in public markets? Will the results of the mid-term elections be well received by the markets?

These are important questions, but they are questions that can be analyzed through fundamentals, valuations, positioning, and market structure. The harder question to answer is how shifts in policy, regulation, fiscal priorities, or geopolitical posture could affect markets. That risk does not lend itself as easily to scenario analysis, but it has meaningful potential to affect the market’s current trajectory. Against that backdrop, we are also watching whether consumer spending and employment remain resilient, whether the path of interest rates continues to pressure valuations, and whether stress in parts of the credit markets remains contained. These considerations are central to how we are thinking about portfolio construction in the second half of 2026.

— Trevor Graham and Jay Willoughby, Co-Chief Investment Officers

Performance, Positioning and Research Priorities

Performance

We expect the liquid portions of our portfolios to range between 1% ahead (most accounts) and 1% behind the public market equivalent benchmark (e.g., 65/35) for Q2. In Public Equities, we will likely end up trailing the benchmark. The largest detractor from performance was from security selection within technology. Our managers have been slightly overweight software and slightly underweight semiconductors and hardware. Given the sharp moves in the latter categories, these small deviations from the benchmark are creating much more noise than they would in a normal environment. The drag from suboptimal tech positioning within our fundamental managers has been offset by outstanding event-driven results in biotech and solid excess return from our multi-manager platforms. Within Diversifiers, our results will likely be well ahead of the Bloomberg Aggregate Index but behind the HFRI FOF Index. We note a somewhat anomalous result in the HFRI Fund of Funds Index. This index usually performs with a beta to equities of about 0.3. The quarter-to-date results that we have as of this publication show HFRI as capturing closer to 55% of the equity market’s return. The result could be due to unusually high alpha (maybe some pre-IPO investments in SpaceX?) or perhaps it is due to net long exposure drifting upwards. Either way, we have decided to maintain the roughly 0.3 equity beta posture of our own portfolio due to the role we want Diversifiers to play, particularly in tougher environments. Positive contributors to results included our systematic strategies, recoveries in our carbon credit positions, and equity long/short managers focused on technology, Europe, and Taiwan.

Most importantly, our overall long-term results continue to be ahead of benchmarks in most time periods.

Positioning

We have not made material adjustments to our basic exposures within Public Equities or Diversifiers. Within Public Equities, we continue to be near the benchmark across geography and sector exposures. However, we have introduced a risk-management tool to reduce factor risk. We have managed geography and sector risk internally with a combination of simple, readily available ETFs, and futures for decades. Managing style factors is not as easy. After a lengthy, multi-year research and testing period, we have added a market-neutral basket of single stocks designed to neutralize more complex unwanted style factor risk. We have been rebalancing this basket monthly as we receive updated holdings from our managers. This adjustment is designed to reduce the portion of our equity tracking error that comes from unintended factor exposures, such as momentum or volatility, and increase the portion that comes from idiosyncratic security selection. This adjustment should result in more consistent excess returns over time.

In early Q2, we added Topwater to portfolios where we believed the strategy fit the portfolio’s objectives. Topwater is a capacity-constrained multi-manager platform with outstanding risk management. We have tracked this manager for years and finally got a chance to invest when a large LP redeemed.

Forward Research Calendar

The team is working on several projects that we expect to reach a conclusion over the second half of the year. We have been researching activist strategies in Japan for the past several years and we expect to add multiple managers in this area over the next quarter. In addition, we are in the late stages of diligence on a new multi-manager platform that we believe may have a competitive advantage in data. In Diversifiers, we are likely to shift some capital to systematic strategies in anticipation of a higher volatility equity environment. These managers tend to have higher turnover than the fundamental managers and adjust their portfolios more quickly.

Beyond manager research, we are working on a project to better evaluate our overall exposure to AI-related businesses. As one of the major growth drivers in the economy, there are now material elements of AI-related exposures across power, energy, utilities, industrials, and business services. Total exposure is a nuanced issue that is not easily quantified with traditional GICS categories. Depending on our findings, we may make some exposure adjustments over Q3.

Recent Firm Highlights

We recently held the final close for our latest private markets direct fund, a strategy that invests in private businesses alongside independent sponsors rather than allocating to private equity funds. The fund was oversubscribed and closed at its hard cap of $300 million. We are currently in the market with our next series of private equity and venture capital fund of funds.

In June, Andrew Murray and Stephen Grau joined TIFF to lead our efforts in private equity secondaries. TIFF has been an active participant in this market for years as both a buyer and a seller, and we believe the combination of limited distributions over the past three years and continued growth in the private equity market has created an attractive investment opportunity. Given that backdrop, we believe our portfolios will benefit from dedicated resources in this area. Read the full press release, here.

We look forward to seeing many of you in Boston on October 28th and 29th at the 2026 TIFF Investment Forum. Thank you for your ongoing partnership and best wishes for a great summer.

These materials are being provided for informational purposes only and constitute neither an offer to sell nor a solicitation of an offer to buy securities. These materials also do not constitute an offer or advertisement of TIFF’s investment advisory services or investment, legal or tax advice. Opinions expressed herein are those of TIFF and are not a recommendation to buy or sell any securities.

These materials may contain forward-looking statements relating to future events. In some cases, you can identify forward-looking statements by terminology such as “may,” “will,” “should,” “expect,” “plan,” “intend,” “anticipate,” “believe,” “estimate,” “predict,” “potential,” or “continue,” the negative of such terms or other comparable terminology. Although TIFF believes the expectations reflected in the forward-looking statements are reasonable, future results cannot be guaranteed. 

Footnotes

  1. FactSet.

  2. TIFF analysis. IPO proceeds — Jay R. Ritter / Univ. of Florida (1990–2014); EY / Renaissance Capital (2015–2026 YTD). Market cap — World Bank / Siblis Research. SpaceX actuals & lock-up — SEC S-1/A, Renaissance Capital 2Q 2026 Review, CNBC, Motley Fool, Investing.com (June 2026). Anthropic/OpenAI — company announcements, Fortune, CNBC, US News (June 2026). 2027 pipeline — Renaissance Capital IPO Outlook. The 2026 SpaceX lock-up calculation includes the conditional release share block.

1st Quarter 2026 CIO Commentary

There are a few large and somewhat unrelated forces shaping markets today. In this letter, we focus on two, particularly the conflict in the Middle East and the evolving impact of AI. While these topics are very different, both introduce significant uncertainty and cause market volatility.

Some Big Moving Pieces and Lessons to Remember

On the first large force shaping markets today: most of us are familiar with the situation unfolding in the Middle East (ME), where the U.S. and Israel are attacking Iran with the stated goals of preventing Iran from obtaining a nuclear weapon, degrading its missile capabilities, limiting its ability to fund terrorism/proxy groups, and securing the Strait of Hormuz, through which roughly 20% of the world’s oil flows. While the ultimate end-state remains somewhat unclear, most U.S. policymakers – who rarely agree – appear aligned in preferring a short conflict and with no U.S. “boots on the ground.” Our goal here is not to choose a side, but to assess what these developments might mean for our portfolios in the short- and long-term. Our goal also is not to ignore the human consequences of this war, which are large and painful. However, our role is to determine whether this development causes materially different investment outcomes than previously considered.

Energy as the Primary Transmission Channel

From an investment perspective, the primary channel through which this conflict affects the global economy is energy prices. Iran has demonstrated its ability to disrupt up to 20% of global oil supply through the Strait of Hormuz by threatening shipping. If flows remain constrained for an extended period, already elevated oil prices could rise further, pushing inflation higher and slowing growth. The chart below shows how a sustained oil shock could impact growth across countries.

2026 GDP Growth Percent Impact Due to Energy Price Shock1

2026 GDP Growth Percent Impact Due to Energy Price Shock

If disruptions ease, prices should normalize more quickly, limiting the impact on inflation and allowing market volatility to subside. Ultimately, a short, successful conflict could lead to a more stable Middle East, reducing some of the geopolitical “risk premium” currently embedded in oil prices, which would support both equity and bond markets.

What Markets Are Pricing

As you can see below, higher price expectations have already been reflected in forward price curves for oil. What matters now is how quickly the Strait reopens. The longer it stays constrained, the larger the supply shortfall becomes — and the higher prices are likely to go.

U.S. Crude WTI Future Curve Before and After Attack on Iran

U.S. Crude WTI Future Curve Before and After Attack on Iran

The range of possible outcomes is best illustrated by how oil markets are currently pricing different scenarios.

Oil Price Expectations Vary Depending on Time Strait Remains Disrupted

The Goldman Sachs chart above illustrates how oil price expectations vary depending on how long the Strait remains disrupted. Forward curves already reflect higher prices, with a prolonged closure likely pushing them higher still.

GS Estimated Impact on Brent 2027Q4 Prices Under Different Strait of Hormuz Disruption and Recovery Scenarios2

GS Estimated Impact on Brent 2027Q4 Prices Under Different Strait of Horuz Disruption and Recovery Scenarios

Recent Developments and Path Forward

On March 22, the U.S. administration warned that failure to reopen the Strait of Hormuz within 48 hours could result in strikes on Iran’s energy infrastructure. Iran responded with warnings of potential retaliation against regional energy assets, shipping routes, and U.S. facilities in the Middle East.

Approximately 36 hours after the initial warning, the U.S. administration paused further escalation, citing “constructive talks with Iran,” a characterization Iranian officials disputed. While both sides have continued limited exchanges, larger-scale offensives appear to have eased, at least temporarily. There are indications that talks may be underway, possibly intensifying with face-to-face meetings in Pakistan. With much of the Iranian leadership removed, it is unclear who ultimately has negotiating authority, which adds another layer of uncertainty. There also appear to be some differences within the remaining Iranian leadership, as most of the oldest hardliners are gone. If a more reformist-minded leader such as President Masoud Pezeshkian ascends, or if the new hardline Supreme Leader Mujtaba Khameini takes a less active role, some experts suggest Iran may become less combative. This would be a positive outcome. If not, the status quo since 1979 or worse may result.

Potential Outcomes

Our view today is cautiously hopeful. If Iran softens its traditional position and the U.S. remains open to an off-ramp, a deal that allows both sides to save face is possible.

The challenge, of course, is that each side’s stated objectives remain far apart. Iran has sought security guarantees, sanctions relief, reparations, removal of U.S. military bases and greater control over the Strait, while the U.S. objectives outlined earlier are largely unacceptable to Iran.

Any resolution would therefore require meaningful concessions from both sides. One possible framework could involve Iran foregoing its pursuit of a nuclear weapon and limiting its missile and drone capabilities, in exchange for security assurances, sanctions relief, and potentially some form of economic support.

While this may seem unlikely today, an outcome that allows both sides to claim some degree of success may be the clearest path to a more stable Middle East. Our hopeful scenario would mark the end of Iran’s 47-year history of destabilization both for themselves and hopefully also for the Middle East. If so, oil prices may embed a permanently lower risk premium. This could lead to lower inflation and stronger global growth in the future.

Lessons for Investors

Against this backdrop, it is worth stepping back and remembering a few lessons that have served investors well:

  1. Warren Buffett’s oft quoted observation: “The stock market is a device for transferring money from the impatient to the patient.”
  2. Over the last four decades, there have been 21 U.S. airstrike campaigns in the MENA region, and eight weeks later the SPX was higher 95% of the time.

Historical Asset Class Performance Eight Weeks After Initial U.S. Airstrike Operations in the Middle East and North Africa3

Historical Asset Class Performance Eight Weeks After Initial U.S. Airstrike Operations in the Middle East and North Africa

Positioning Implications

With global equity markets down nearly 7% since the conflict began, and analysts’ earnings estimates showing continued upward revisions in the U.S., we sense some modest upside potential in stocks. While we are not taking large positions in the portfolio in either direction based upon what we know and what we’ve heard, we do own a few small bullish call option positions that would benefit the portfolio some if this were to occur. Additionally, we are keeping a close eye on 10-year Treasury yields. A break above 4.5% would interest us, as any energy inspired inflation would likely revert quickly if a deal can be struck, allowing rates to fall back to lower levels. If we are wrong and conditions in the ME deteriorate further, we will be positioned very close to our benchmarks and will have all the flexibility to make more impactful changes after better opportunities have presented themselves.

The range of possible outcomes in the Middle East is very wide, and the ramifications if energy or desalination infrastructure is struck and / or more countries join the fray should not be underestimated. However, while geopolitics may be driving incredible near-term market uncertainty (even hour by hour), a separate and potentially more impactful force is shaping longer-term market expectations: the impact of AI.

AI’s Impact on Jobs and the Economy

A central question in markets today is AI’s potential impact on the economy and employment. Past technological advances have helped humans live safer and easier lives (fire/electricity), move goods and people more efficiently (the wheel/trains/cars), communicate faster (telephones/the internet), and make better decisions (computers/software). AI may be different. For the first time, we may be developing a technology capable of thinking and making decisions in place of humans, raising important questions about employment and long-term economic growth.

Bear Case: Those who believe AI can disintermediate jobs quickly see a technology that works non-stop without supervision and improves itself at an ever-increasing pace. You don’t pay it a wage or health care benefits, it never sleeps or complains, and if it cannot do what you want today, it likely will in a few weeks (or less). (And this is putting aside the ultimate Bear case, which envisions a dystopian humankind versus machine battle.)

Bull Case: Those who believe AI won’t take all of our jobs point to its lack of 1) human creativity or 2) access to all data (as critical databases are inaccessible because uninvited sharing of sensitive data could be an existential threat). They believe that, like previous technological advances, AI will free humans to focus on higher-value work, increasing productivity and creating jobs we cannot yet imagine, much like a software engineer could not have been imagined before a computer was invented.

The Potential SaaSpocalypse

Ground zero of this debate is the SaaS (software as a service) stocks. There are others, but AI believers expect that, over time, companies will be able to task their own internal AI to build software stacks that replace some of the SaaS services they currently use for internal processes. They believe companies understand their own “hotspots” and where they cannot afford software mistakes and will continue to test in-house AI-developed solutions until they are reliable. While these solutions may not be ready to take over from current vendors today, they could be more viable in the future.

Those who doubt AI will rapidly cannibalize jobs see AI as a productivity accelerator. They believe in the human processes that require time to investigate, understand, gain trust, run trials, debug, and then slowly begin to implement a solution that may represent an existential decision. If you implement a big change to your enterprise resource planning (ERP) process (software) you are betting your company on it working.

Before tackling an example, it is worth briefly defining what ERP software does: it “pulls data and workflows from finance, supply chain, HR, sales, and other functions into a single platform, allowing a company to operate on one consistent set of real-time information.”

One of the best examples of this dynamic is SAP, a company several of our managers own. SAP is one of the leading global providers of enterprise resource planning (ERP) software and is also working to incorporate AI into its own offerings.

Importantly, the company’s fundamentals remain strong. Revenues and earnings are expected to grow at an accelerating pace over the next several years, with consensus estimates pointing to continued double-digit earnings growth.

Revenues and Earnings
Source: Bloomberg. In USD as of 03/25/26 at 11:50AM.

That is a very attractive earnings profile! With the stock today at $176, that is a PE of 21x 2026 and only 11.3x 2030 earnings estimates. The average PE over the last 10 years is 31x.

Nevertheless, the stock price has declined by 28% YTD and is down 44% from its July 2025 high. This is not due to weakening near-term earnings, but rather a reassessment of the durability of the business. The market is increasingly pricing in potential AI-driven erosion of SAP’s franchise and terminal value.

As a result, earnings are rising while the stock is falling — a reminder that markets are forward-looking discounting mechanisms. At times, investors simply do not believe the future will look as strong as the past, regardless of current earnings estimates.

Currently, it is hard for the SAP bulls to combat the AI believer’s assertions. Only time will tell if AI will become another tool, assimilated in the same way the internet was, creating some of the greatest businesses ever – think Google and Amazon, or if in time AI will take over all aspects of what SAP (and many companies) currently does for its customers and slowly (but quickly when it comes) put them out of business. As we sit here today, the AI bulls appear to be winning, but several of our managers believe this is creating attractive opportunities for new investments.

Productivity and the Power Constraint

We are more aligned with the bulls. Our current belief is that AI will become more pervasive across corporate America. It will make businesses large and small more productive. Rising productivity enhances living standards and tends to reduce inflation. AI can help with both. We have been using AI in our investment process and firm operations and have indeed been astounded by its capabilities when prompted well. (As an interesting example, please see the Appendix which combines AI insights with the Middle East War.)

The limiting constraint to AI growth may be electricity generation. We continue to push the grid, because we need ever more power in order to grow AI at the breakneck speeds we have to this point. Substituting AI for people will require more electricity. Some investors argue that the productivity improvement AI brings may be meaningfully offset by the increased cost of powering the AI. It seems unlikely that AI electricity will cost more than a human, but the scale and cost of the required electricity build out could surprise us all.

This is a complex situation. AI has the potential to make the global economy more efficient — provided it augments, rather than replaces, human work.

Capital Expenditure of U.S. Investor-Owned Electric Utilities vs. U.S. Electricity Demand4

Capital Expenditure of U.S. Investor-Owned Electric Utilities vs. U.S. Electricity Demand

Today’s Positioning

Bringing these topics together, we turn to how we are positioning portfolios.

We have not made major changes to our strategic asset allocation or overall portfolio construction. Within equities, we remain close to benchmark on “Level 1” factor exposures such as sector and geography, while maintaining our longstanding modest underweight to megacap stocks in favor of medium (mostly) and small cap companies. Despite limited factor risk, the portfolio continues to reflect our highest-conviction ideas, with most deviation from the benchmark driven by idiosyncratic security selection.

Within diversifiers, we maintain exposure to a mix of strategies designed to have low correlations to one another, and we have recently added merger arbitrage and equity capital markets strategies in anticipation of increased corporate activity.

Within fixed income, we remain short duration, reflecting concerns about the U.S.’ deteriorating fiscal position and the potential for higher inflation if the situation in the Middle East worsens.

While we are always looking for tactical opportunities, we recognize these are among the most difficult decisions to get right. Historically, the most attractive opportunities have come when sentiment is extremely negative. Today, markets are highly focused on developments in the Middle East, and unless disruption escalates meaningfully, a compelling entry point may not emerge. While that is not a desirable outcome, we would be prepared to respond if conditions were to deteriorate. Should tensions escalate further—through broader regional conflict or a prolonged disruption to the Strait of Hormuz—opportunities may develop later in the year. For now, we remain balanced and flexible, relying on security selection to drive value, as we have over most of TIFF’s history.

Despite a difficult start to the year, the investment backdrop could still improve as we move forward. If earnings estimates remain firm and inflation pressures from energy prove temporary, 2026 could still be a positive year for markets. While uncertainty is elevated, markets have handled it relatively well. A short conflict with no U.S. boots on the ground would likely represent the most favorable outcome for markets.

As always, we greatly appreciate the opportunity to manage your capital and help you achieve your organization’s goals. We are here to assist in any way possible, so please feel free to reach out to us with any questions or needs.

Your TIFF Investment Team


Appendix: Applying AI Capabilities to Middle East War Potential Outcomes

Additional Context on the War in Iran

Because the range of potential outcomes in the Middle East is unusually wide, we used AI as a tool to help frame possible scenarios and stress-test our thinking. It is important to emphasize that AI is not used to make investment decisions, but rather to extend the team’s research capabilities and explore a broader set of inputs and perspectives.

For this exercise, we asked a well-known Large Language Model (LLM) AI engine (on March 24, 2026) to outline what it viewed as the most likely scenarios based on its synthesis of a large body of available information (the underlying analysis drew from hundreds of sources). What follows is a condensed version of that output. These scenarios do not represent the views of the TIFF team, nor should they be interpreted as forecasts. As with any model, the results are sensitive to changing inputs, and different conditions or prompts would likely produce different outcomes. We hope you find this content useful.

Strait of Hormuz Crisis: Scenario Analysis
The March 28 Deadline and What Comes Next

Current State of Play

Twenty-five days into the U.S.-Israeli military campaign against Iran, the air war is largely won — over 9,000 targets struck, 140+ naval vessels destroyed, missile launch rates down roughly 90%. But Iran’s most consequential weapon remains deployed: the effective closure of the Strait of Hormuz. Tanker transits have collapsed 94% from pre-war levels. The IEA has called this the largest supply disruption in the history of the global oil market. On March 21, Trump issued an ultimatum demanding Iran fully reopen the Strait within 48 hours or face strikes on power infrastructure. That deadline was postponed five days on March 23 after the administration claimed productive conversations with Iran through mediators. Tehran has denied direct talks. As of March 24, fighting continues: Israel launched fresh strikes on Tehran; Iran fired ballistic missiles at Tel Aviv and hit a Kuwaiti oil refinery. Pakistan has offered to host in-person negotiations. The new deadline expires Saturday, March 28.

Three Scenarios from the March 28 Deadline

Scenario A — Negotiated De-escalation (~30%)

Backchannel talks produce a framework agreement by early April. Iran agrees to phased Strait reopening in exchange for a halt to energy infrastructure strikes and a pathway toward broader negotiations. Brent retreats to $75–85 by end of Q2, settling near $70–75 by Q4 as flows normalize. GDP drag is contained to roughly -0.3 to -0.5 percentage points for full-year 2026. Headline CPI spikes to 3.0–3.5% in Q2 before moderating. The Fed holds through June and delivers one or two 25bp cuts in H2. Recession is avoided. Key trigger: Any confirmed in-person meeting between US and Iranian representatives, or a visible increase in Hormuz tanker transits from the current 4–5 per day toward 20+.

Scenario B — Protracted Standoff (~45%)

The most likely outcome. March 28 passes without resolution. Trump may extend deadlines, impose limited additional strikes on non-energy targets, or begin selective strikes while claiming a phased approach. Iran maintains the Strait’s contested status using mines, drone threats, and the $2 million per-transit toll it has already imposed. The conflict shifts from intense kinetic operations to a grinding attritional phase. Houthi entry becomes probable, extending maritime disruption to the Bab el-Mandeb. Brent oscillates in a $95–120 band through Q2, with spikes above $120 on escalation headlines. A sustained $30–40 increase from pre-war WTI levels implies -0.30 to -0.40pp of GDP drag and +0.84 to +1.12pp on headline CPI. Core PCE reaches 2.8–3.2%. Recession probability rises to 35–45%. The Fed remains frozen — unable to cut into rising inflation, unwilling to hike into weakening growth. Key trigger: Houthi military action in the Red Sea or Bab el-Mandeb, or further Iranian drone strikes on Saudi Arabia’s Yanbu bypass port.

Scenario C — Escalation Spiral (~25%)

March 28 passes and Trump orders strikes on Iranian power plants and energy infrastructure. Iran retaliates by mining the entire Persian Gulf, striking Gulf state desalination plants (90%+ of freshwater supply), and ordering Houthi attacks on Red Sea shipping simultaneously. Brent breaches $130–150, potentially exceeding the 2008 record. Goldman’s extreme scenario envisions daily prices above $147. Gas prices nationally exceed $5.50–6.00/gallon. Recession becomes the base case: Dallas Fed modeling shows oil at $132 by year-end with growth remaining negative. The Fed faces a Volcker-era dilemma. Credit markets, currently showing modest stress (HY spreads at the 38th percentile), widen violently. Key trigger: Any strike on Iranian power generation infrastructure — Iran’s explicit threat to mine the entire Gulf in response makes this a bright-line escalation event.

Note: These three scenarios sum to roughly 100% of estimated probability. A 5–10% residual tail of outcomes outside this framework exists — most notably regime collapse in Tehran, a Chinese-brokered grand bargain, or a direct Iranian nuclear test — each carrying non-linear market implications that resist probabilistic framing.

Decision-Relevant Signposts

The single highest-leverage variable is the physical status of the Strait of Hormuz. Windward and Lloyd’s List Intelligence provide near-real-time tanker tracking — any sustained increase above 20 transits per day would confirm de-escalation before official announcements. Beyond that: the March 28 deadline outcome, any Houthi belligerency declaration, the April 5 OPEC+ meeting (spare capacity sits on the wrong side of the Strait), and the April 28–29 FOMC (the Fed’s next decision point on whether oil-driven inflation merits a hawkish pivot).

What This Means for Long-Term Allocators

The range of plausible outcomes over the next 60 days is unusually wide — spanning from a swift normalization that unwinds the oil risk premium to a sustained supply crisis that tips the US economy into recession. For institutional investors with multi-decade horizons, the analytical frame matters more than any single scenario: the most decision-relevant variable is not oil prices themselves but the duration of the Strait’s disruption, which determines whether the shock is a transient repricing or a structural regime change in energy, inflation, and growth. History favors the transient outcome, but history has never seen 20% of global petroleum transit shut simultaneously for this long.


End Notes

The materials are being provided for informational purposes only and constitute neither an offer to sell nor a solicitation of an offer to buy securities. These materials also do not constitute an offer or advertisement of TIFF’s investment advisory services or investment, legal or tax advice. Opinions expressed herein are those of TIFF and are not a recommendation to buy or sell any securities.

These materials may contain forward-looking statements relating to future events. In some cases, you can identify forward-looking statements by terminology such as “may,” “will,” “should,” “expect,” “plan,” “intend,” “anticipate,” “believe,” “estimate,” “predict,” “potential,” or “continue,” the negative of such terms or other comparable terminology. Although TIFF believes the expectations reflected in the forward-looking statements are reasonable, future results cannot be guaranteed.

Footnotes

  1. Source: Eurasia Group.

  2. Source: Goldman Sachs Global Investment Research. The estimated impact is relative to GS pre-war forecast for Brent 2027Q4 at $69/bbl. Days of disruptions indicate number of days when flows through the Strait of Hormuz are below 10% of normal. GS assumes a gradual 30-day recovery after the initial disruption window is over.

  3. Source: Goldman Sachs Investment Strategy Group, Turning Point Market Research.

  4. Source: ICF analysis of power industry forecast and planning documents, EEI.

4th Quarter 2025 CIO Commentary

Executive Summary

  • 2026 is “game time.” The year ahead should help answer whether the One Big Beautiful Bill (OBBB) supports growth and disinflation, whether deficits can be reined in, and whether the AI boom is durable—or a bubble.
  • OBBB could be a net positive for growth and possibly inflation. We expect tax cuts and investment incentives to support jobs and productivity, potentially keeping inflation contained and giving the Fed room to ease.
  • The budget deficit remains the biggest long-rate risk. With U.S. debt cited at approximately $38.4T by year-end 2025 and still rising, we remain cautious on long duration and mindful of dollar risk.
  • Tariffs may change form, but the peak shock has likely passed. Even if current tariffs are overturned and later re-implemented under different authorities, we expect the worst of the tariff impulse is behind us.
  • AI remains in the middle innings, but scrutiny is rising. Hyperscalers’ 2026 capex is cited at approximately $550–$600B and potentially much more in aggregate, meaning markets will increasingly demand proof of broad adoption and real returns.
  • Outlook and positioning remain constructive, with more volatility. We expect a more two-sided equity market with bigger swings and mid-single-digit gains as a base case, while staying fully invested and close to policy targets. We are modestly overweight healthcare, roughly market weight “Mag 7,” short fixed-income duration, with a slight underweight to the U.S. dollar.

Game Time

Happy New Year! At least that is our hope as we turn the calendar to 2026. While we are optimistic, we are not certain that capital markets will maintain the same excellent streak they’ve enjoyed since 2022. The year ahead may be when we find out if the administrations’ One Big Beautiful Bill (OBBB) actually helps the economy and brings down inflation (we still believe it can), whether U.S. budget deficits can be reined in relative to GDP growth (we doubt it), and finally whether markets are in an AI bubble or if AI can justify all the “pre-game” hype (we are cautiously optimistic).

Because the OBBB cuts taxes for both households and businesses and provides more generous investment incentives, we remain optimistic about prospects for the U.S. economy. Arthur Laffer once asked, “If I tax you 100%, would you work more? If I eliminated your taxes and let you keep everything you make, would you work more?” Everyone in the room agreed that this was not a realistic choice, but that if it was, they would work more if they got to keep more.

We are hopeful that people still feel this way and that the economy will have more people working and more investment supporting these additional jobs. In particular, it would be nice if by exempting taxes on tips and certain overtime, combined with certain child- and work-related credits, the OBBB could help reduce pay inequality. Naysayers don’t bother us; in today’s world, it seems no program can please all of the people. We remain optimistic about the OBBB.

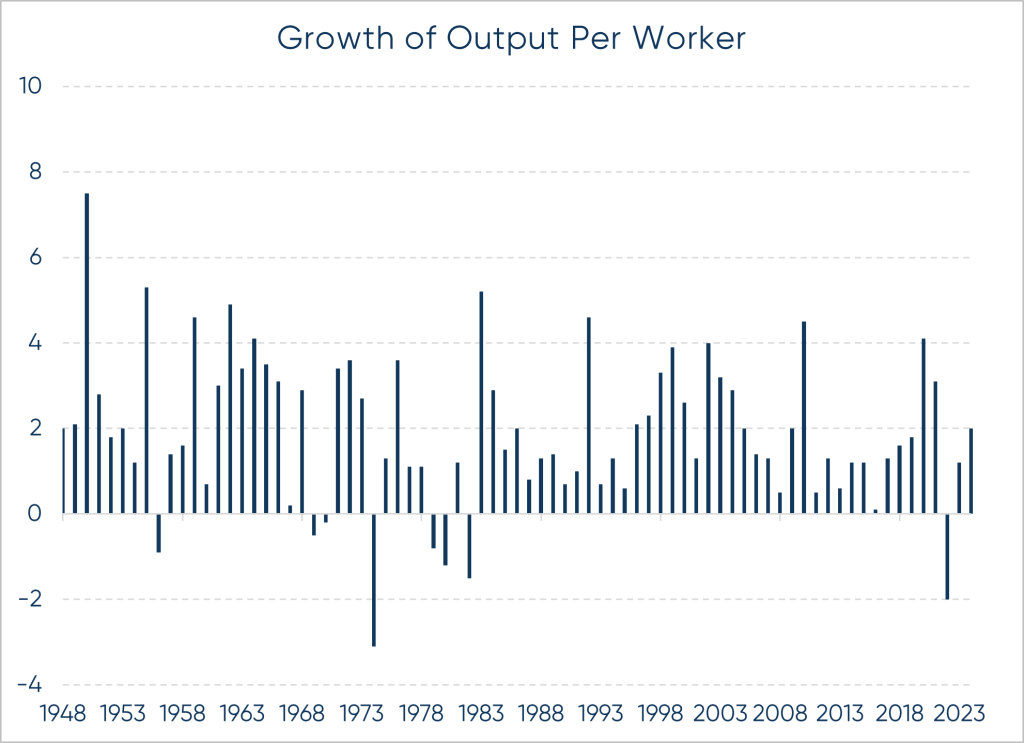
If the economy does remain solid—or accelerate some as the previous paragraph optimistically intimates—it is possible that inflation stays tame. As Milton Friedman famously said, “inflation is always and everywhere a monetary phenomenon.” Translated: it is too much money chasing too few goods. By stimulating investment and jobs, productivity can rise, and the supply of goods hopefully grow at least as quickly as demand. This is a balancing act that could result in stable or even slightly lower inflation levels, which would allow the Fed to reduce short-term rates some. Additionally, and importantly, just as the internet build-out led to higher productivity in the late 1990s and early 2000s period, AI has similar potential to similarly increase productivity.

Prospects for a New Productivity Upswing: Evidence from Historical Periods1

Growth of Output Per Worker

As we write, markets are anticipating the Fed to cut short-term rates by 25 basis points two more times by September 2026. Normally, when the Fed reduces short-term rates, mortgage rates and other borrowing costs fall as well, stimulating further economic growth. Our fingers are crossed that this benign environment can eventuate as it would likely not just be good for short-term interest rates and the economy, but also for the bond and equity markets.

The Setup: Deficits, Tariffs, and Inflation

Much of what we hear on tariffs is that they are likely to be over-turned ruled by the U.S. Supreme Court. It isn’t clear whether the government would be required to provide refunds, but tariffs are unlikely to be allowed as structured today. We fully expect the administration to implement a revised version of tariffs under a new executive order, using different emergency powers or trade acts. Regardless, we expect that we’ve seen the worst of the tariff and that is a good thing. With that policy backdrop, the key market question is what all of this means for inflation and interest rates.

In general, bonds are pretty simple. If a three-month Treasury bill yields 4% and rates are not expected to decline, then a six-month T-bill will typically yield a little more than 4% due to the slightly longer duration. The same principle applies to a 12-month T-bill relative to a 6-month and extends all the way to the 30-year Treasury bond. When investors expect rates to rise or fall based on expected changes in future inflation, the shape of the yield curve can change. Lower rate expectations typically bring the entire interest rate curve lower and vice versa.

So, the yield curve is mostly math plus expectations, which brings us to our biggest concern about long-term rates today: how much debt the U.S. will issue, and what investors will demand to finance it.

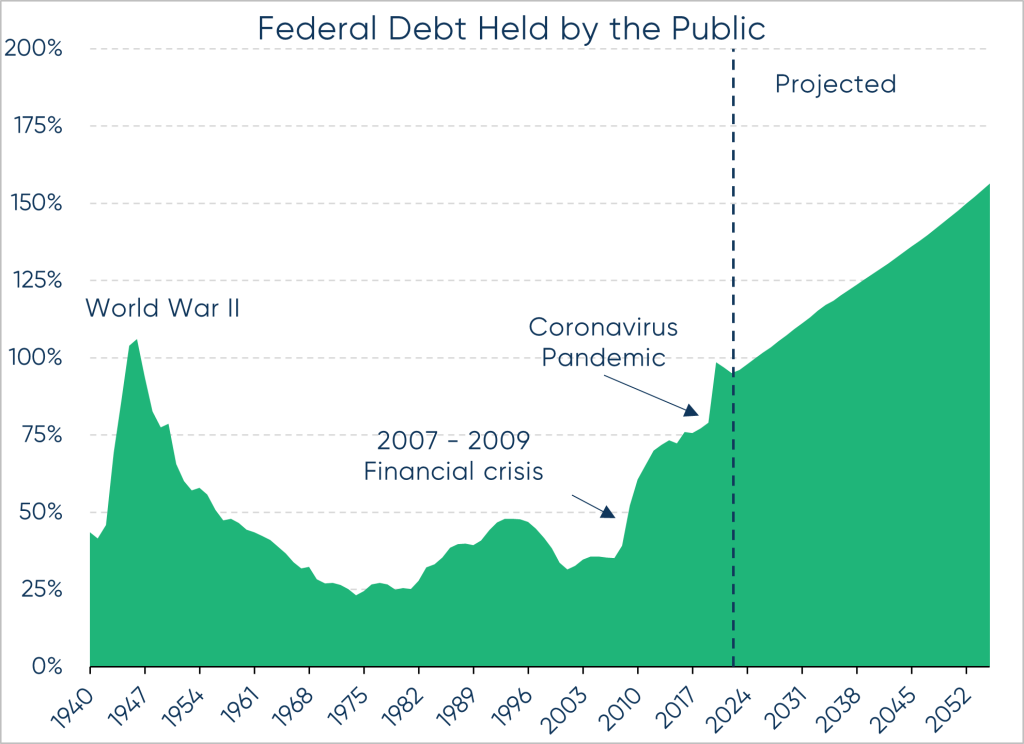
The massive pile of U.S. debt continues to grow, reaching $38.4 trillion by year-end 2025. According to the Congressional Budget Office (CBO), debt growth of $1.9 trillion in 2025 will accelerate to $2.6 trillion by 2035, with total debt expected to reach $138 trillion by 2055. At the current pace, we are expected to add $100 trillion in debt in the next 30 years. This level is expected to equal an estimated 156% of GDP in 2055, up from approximately 100% today! In our minds, this is not sustainable.

This also explains why markets are nervous about U.S. dollar risk. Historically, rather than make the hard decisions about how to balance a country’s budget, politicians have taken the “easy” path—inflating their way out. Devaluing the currency hurts everyone, but bondholders get hurt the worst as they are repaid in less valuable currency than expected. This simple fact keeps us nervous about letting our duration get too long. We remain cautiously positioned today at 4.25 years versus roughly 6.10 years for the Bloomberg Aggregate Index.

All this said, any progress on lowering inflation would be good for bond prices, and if the OBBB were to help bring some balance to government financing, it could lead to lower interest rates than we currently expect. The reasonably low starting interest rate of 4.1% on the 10-year Treasury, however, causes us to believe that even in that environment, extending duration is unlikely to prove helpful for future returns. As we’ve said before, if/as rates move higher, we would be inclined to extend our duration marginally.

The Deficit is Rising Higher and More Quickly than Ever Before2

Federal Debt Held by the Public

Another factor shaping the longer-term outlook for inflation and interest rates is the scale of investment our trading partners have proposed in the U.S. Many of these commitments may take years to materialize—if they materialize at all—but those that do could influence growth, inflation, and capital demand well beyond this administration.

A meaningful share of this spending is likely to support the physical build-out required to stay competitive in AI. Leadership in AI will require far greater power generation and grid capacity. Current estimates suggest that roughly $1.1 trillion will need to be invested by 2029 to meet projected AI-driven electricity demand of 123 gigawatts by 2035, up from 4 gigawatts in 2024. Progress on permitting and regulatory reform—also promised in the OBBB—will be critical to enabling this build-out.

AI: Middle Innings or Bubble?

Our optimistic equity outlook has served us well over the past three years. As we enter 2026, we remain constructive, but with greater caution. We expect a more two-sided stock market, with larger swings both up and down, ultimately pointing to mid-single-digit gains. That said, outcomes could deviate meaningfully: a strong or weak finish could shift returns by 20% in either direction, or we could simply be wrong in our assessment. Let us explain.

The late-2022 announcement of ChatGPT may have been the catalyst for the 2023 advance and has continued to power markets since. Elon Musk recently claimed that in 10-20 years, work will be optional, like growing your own vegetables is today. Not mandatory, but a choice. He believes AI and robotics will create an “age of abundance” in which goods and services become nearly free. While this may or may not prove true, it has investors thinking that the rewards of backing the right companies could produce huge profits in the stock market. The largest and most profitable companies in the world are now spending more on building out datacenters and AI capabilities than would have been imaginable just three years ago. Each company views winning in the AI race as existential.

Something similar happened 30 years ago when the internet captured investors’ imaginations. A group of tech companies spent heavily to build out the internet. It ended up producing enormous benefits for society, but also a bubble in stock market values that later collapsed. The leading stock at the time, Cisco Systems, rose to $82 per share in March 2000 from $0.14 in January 1991. While Cisco has been a successful company over the last 25 years, it has yet to reclaim its 2000 high.

This concern exists today for some of the leading AI companies. After three years of strong gains, we expect to glean some clarity in 2026 on whether or not this technology and these companies are real and can change the world, or whether this is another bubble similar to the internet boom. We expect more back and forth in 2026 than we’ve seen to this point.

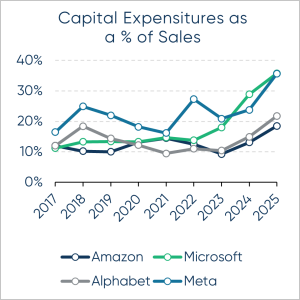
Mag 7 valuations are elevated and have pulled overall market valuations higher. Strong earnings growth has thus far justified the premium, with expectations for continued growth into 2026. As long as these companies deliver, both they and the broader market can keep moving higher. The risk, of course, is that growth slows. High valuations, paired with moderating earnings and significant capital spending, would represent a headwind for both the group and the broader market.

At some point, that scenario is likely, but we believe we are still in the middle innings of the AI cycle, not the later ones. Ultimately, AI has the potential to become ubiquitous in cars, robots, and beyond. If GDP is a function of the size of the workforce multiplied by productivity, and robots can increasingly perform human tasks, then GDP growth could rise well beyond current limits. Such an outcome could usher in an age of abundance marked by stronger growth and lower inflation.

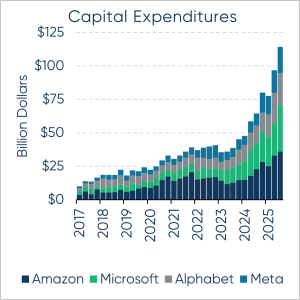
That doesn’t mean stocks will go straight up. We expect this year will be more two-sided, with the bull argument and the bear argument each dominating at different times. All the talk about what AI can and will do will be more carefully scrutinized by investors. The massive sums of capital being invested will need to produce returns to justify further investment. Without justification, investors may move to the sidelines, and the stocks could decline. Capex projections for hyperscalers in 2026 are approximately $550-600 billion. Including other participants, capex could reach as much as $2 trillion by some estimates. Without signs of broader adoption across corporate America and beyond, this level of spending will likely trigger a retrenchment in stock prices.

Balancing Elevated Valuations with Record Capital Spending3

Capital Expenditures as a % of Sales

It’s hard to be certain how the year may unfold, but we do believe one side of this debate may be in vogue for a time, only to be replaced by the other later in the year. This dynamic could repeat more than once. When we get to the end of the year, we don’t think it will be “decided”, but we do think we will be closer to understanding whether AI is a bubble or possibly the most important development of our lives.

Regardless, we start 2026 with very high valuations and expect that downside moves could be larger than we’ve seen in a few years. We are also aware that the last three years have been particularly strong, producing three-year compound SPX returns north of 20%. The last periods with comparable returns were 2021 and 1999, which were both followed by bad equity markets in 2022 and 2000. This doesn’t mean stocks will fall but does remind us that if fundamentals do change, markets have come a long way and could retrace some of those gains. In the end, modest inflation, an easing Fed, a resilient consumer, and expected low-double-digit earnings growth cause us to believe that when we ring in 2027, we will be capping another positive year—though possibly one that requires some hand wringing along the way.

Finally, on this subject, we regularly remind ourselves that markets are rational, even if investors sometimes are not. The market looks forward and discounts earnings back to a current value of expected future earnings discounted back at an appropriate risk-adjusted rate. High current valuations are not a reason to sell stocks, but they are a good indication that if expectations are not met, the potential downside may be larger than average. As long as the future continues to get brighter, stocks can continue to rise.

The more investors doubt that stocks can rise, the more cash on the sidelines waiting for a pullback. If stocks don’t pull back, then one by one those sidelined investors re-enter the market and push prices higher. Once everyone (proverbially) is fully invested and conditions change, that is when the market peaks and begins its decline. This is what makes calling tops so difficult.

As we move through 2026, we won’t be trying to call a top per se, but we do hope to rebalance out of winners and into underperformers, and vice versa, at appropriate times. Rebalancing and dollar cost averaging are your friends. We try not to forget that.

Today’s Positioning

Today we remain fully invested and broadly aligned with our strategic asset allocation targets for our client portfolios. We are not taking any meaningful geographic over- or underweights versus well-known indices. Within equities, we hold a modest overweight to healthcare—a sector that has lagged in recent years but one we believe could benefit from AI adoption. We also think RFK-related concerns have largely peaked, creating room for valuations to improve. Our position in the Mag 7 is roughly market weight; these companies continue to generate substantial cash flow to fund future investment, and in our view, at least one or two are likely to be long-term winners if AI unfolds as expected.

In fixed income, we continue to run short duration and maintain a slight underweight to the U.S. dollar, given our fiscal concerns.  Our hedge fund portfolios are again expected to provide better returns with similar or better ballast than fixed income.

2025 was another good year for markets—the third in a row. Here’s to a solid 2026 as well, even if we expect a bumpier path and a few more lead changes along the way.

As always, we greatly appreciate the opportunity to manage your capital and help you achieve your organization’s goals. We are here to assist so please feel free to reach out with any questions or needs.

Your TIFF Investment Team

Past performance is no guarantee of future results and the opinions presented cannot be viewed as an indicator of future performance. There is no guarantee that any particular asset allocation or mix of strategies will meet your investment objectives.

The materials are being provided for informational purposes only and constitute neither an offer to sell nor a solicitation of an offer to buy securities. These materials also do not constitute investment, legal or tax advice. Opinions expressed herein are those of TIFF and are not a recommendation to buy or sell any securities.

These materials may contain forward-looking statements relating to future events. In some cases, you can identify forward-looking statements by terminology such as “may,” “will,” “should,” “expect,” “plan,” “intend,” “anticipate,” “believe,” “estimate,” “predict,” “potential,” or “continue,” the negative of such terms or other comparable terminology. Although TIFF believes the expectations reflected in the forward-looking statements are reasonable, future results cannot be guaranteed.

Footnotes

  1. Federal Reserve Bank of San Francisco, data on growth of output per worker.

  2. Congressional Budget Office, federal debt projections.

  3. Company disclosures and Wall Street Journal reporting.

3rd Quarter 2025 CIO Commentary

Executive Summary

  • U.S. exceptionalism remains intact: We continue to see the U.S. as the world’s economic leader and believe equities remain the most resilient long-term store of value. We are mildly underweight bonds (both notional and duration-adjusted) given fiscal concerns.
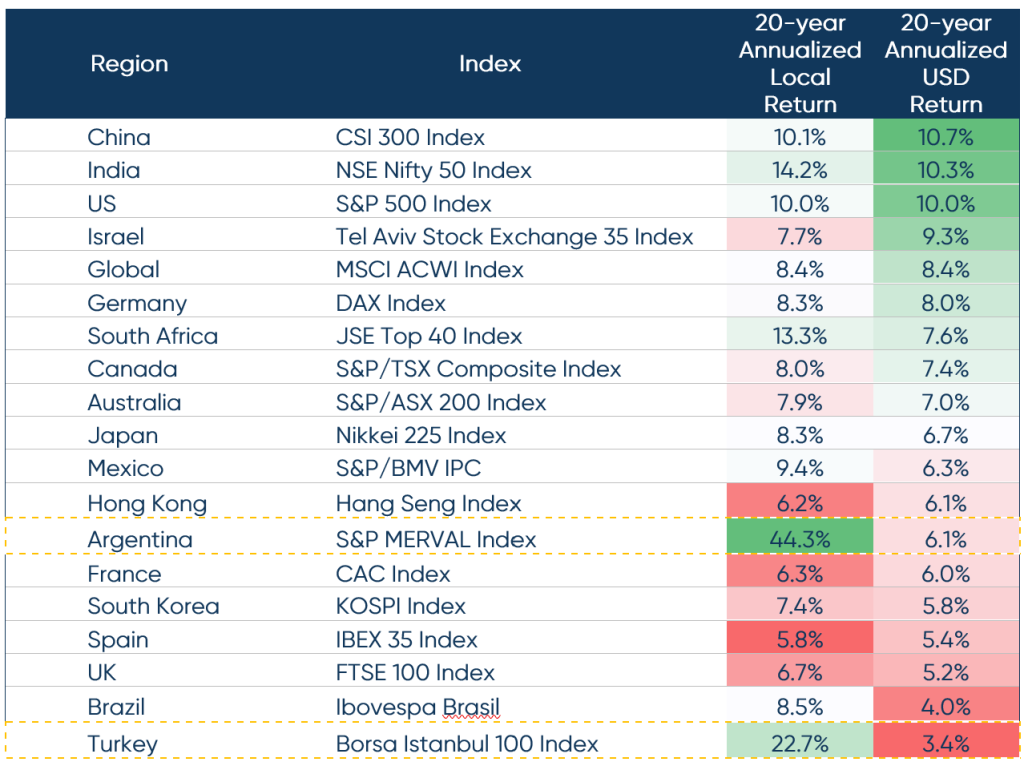
  • What other markets teach us: Argentina and Turkey’s stellar local-currency returns are not signs of economic health; currency depreciation tells the fuller story. When translated to USD, their markets no longer outpace the U.S./ACWI, yet equities there still delivered positive real-asset exposure through turmoil.
  • Deficits and dollar risk warrant attention: The U.S. must sell roughly $2T of new debt each year. If foreign demand wanes, rates could rise and the dollar could weaken. That would slightly reduce the appeal of U.S. stocks for foreign buyers and could pressure bonds.
  • Practical safeguards: Sensible steps include reviewing dollar exposure, maintaining global diversification, and holding proven real-asset hedges like gold; bitcoin may also play a limited role for some. Even so, owning equity remains the most universal hedge against inflation and currency decay.
  • Current positioning: After ~30% gains from April lows, we are at target equity exposure and carry modest equity puts as inexpensive insurance into typical September–October chop.

U.S. Exceptionalism, Risks, and the Case for Equities

Despite unsettling headlines, we believe United States exceptionalism endures. As we wrote last quarter, we believe the U.S. will remain the economic leader of the world for the foreseeable future and that leadership will continue to translate into strong long-term returns. While U.S. fiscal deficits and potential pressure on the dollar deserve attention, and those concerns cause us to be mildly underweight bonds (on both a notional and duration-adjusted basis), we still see equities as an effective and resilient long-term store of value.

Lessons from Abroad

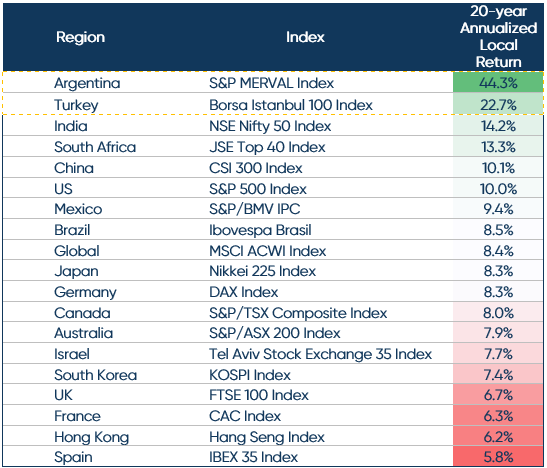
Below is a table of the best-performing stock market indices over the past 20 years, with returns denominated in local currency. For comparison, we have also included the S&P 500 and the MSCI All Country World index (both denominated in U.S. dollars). As shown in the table below, ACWI and the SPX have produced compound returns over that stretch of 8.4% and 10.0%, respectively, which is better than most investors expect going forward.

Net Total Return Local Index (Net of Dividends) Ended July 31, 2025

Net Total Return Local Index (Net of Dividends) Ended July 31, 2025
Source: Bloomberg, MSCI, and S&P Dow Jones Indices. Net Total Return Local Indices, 20 years ended July 31, 2025.

The two top-performing markets on this chart, Argentina and Turkey, have significantly outperformed the global and U.S. benchmarks, but their story is not one of economic strength.

Argentina’s experience is instructive. Chronic fiscal deficits, runaway inflation, and repeated currency crises drove the peso from roughly 3 per U.S. dollar to roughly 1,400 to 1! Over the past 20 years, living standards have fallen sharply, savings have been destroyed, and confidence in the currency has evaporated. In recent years, the peso lost nearly all credibility as a store of value, with many Argentines preferring to transact in U.S. dollars or other hard currencies whenever possible. This cycle of crisis and inflation repeated multiple times over two decades, preventing lasting stability and demonstrating the importance of strong fiscal and monetary institutions for currency stability.

The U.S. Dollar and Deficit Risk

However, the U.S. is not Argentina. Our institutions are stronger, our economy far more dynamic, our currency is still the world’s reserve, and most major commodities are transacted predominantly in U.S. dollars. That said, persistent deficits create risks. The U.S. government must sell roughly $2 trillion in new debt each year. If foreign demand weakens, higher interest rates and downward pressure on the dollar could follow—reducing the appeal of U.S. debt and eroding purchasing power for bondholders.

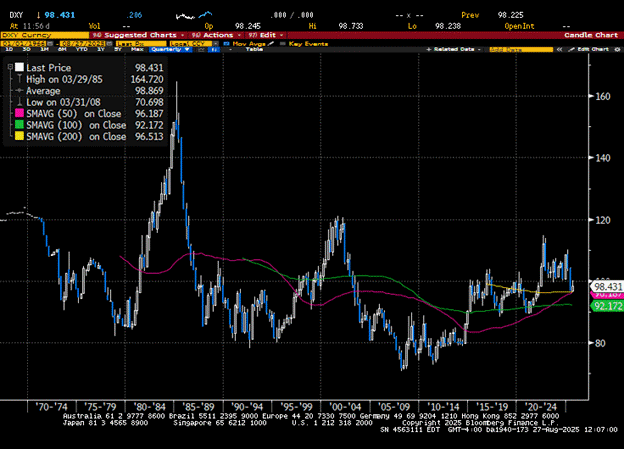
The chart below shows the long-term trend of the U.S. dollar (with DXY measuring its general international value by averaging its exchange rates against major world currencies). Today the dollar sits near its long-term average value versus major peers, suggesting to us that the U.S. dollar is somewhere near fairly valued. Confidence remains solid, but fiscal discipline will matter.

We are concerned that if the fiscal situation is not addressed, three impacts may follow. First, the U.S. dollar could depreciate, which would imply that we, as global investors, should increase our international holdings—a step we have not taken to date. Second, the U.S. stock market could become marginally less attractive as foreign investors worry about stock market gains being offset by currency losses. Finally, bonds could sell off, in some cases materially.

The U.S. Dollar and Deficit Risk
Source: Bloomberg, U.S. Dollar Index (DXY), Dec. 1969–July 2025.

Ways to Try and Safeguard Your Capital

Investors do have potential shelters to turn to. Throughout history, investors have looked to real assets when currencies waver. Gold, for example, has risen nearly ninefold over the past 20 years, roughly matching the performance of U.S. stocks. Bitcoin, though newer and more volatile, has also gained some acceptance as a store of value outside government control.

While we believe modest portfolio adjustments, such as examining dollar exposure, maintaining a global portfolio, and owning “safe havens” like gold and bitcoin as a hedge against possible dollar depreciation may be beneficial, we still view equities as the most practical and universal hedge. Investing in stocks may be the simplest way to hedge against inflation, however, because stocks offer exposure to real economic growth, pricing power, and global demand. They allow holders to participate in the hard work and innovation of employees and to benefit from the pricing power that companies can exercise.

The same chart from above, with returns adjusted into U.S. dollars (see below), shows Argentine and Turkish stocks no longer exceeding the U.S. or ACWI. Yet even these countries’ economically challenged markets have delivered positive returns in the face of massive uncertainty. Unlike bonds, which can be eroded by inflation and currency depreciation, equities have shown resilience—even in countries facing deep crises. And global investors tend to reprice companies toward fair value, creating a natural hedge against local currency weakness.

Net Total Return Index (Net of Dividends) Ended July 31, 2025

Net Total Return Index (Net of Dividends)
Source: Bloomberg, MSCI, and S&P Dow Jones Indices. Net Total Return Indices (local currency and USD), 20 years ended July 31, 2025.

This is not to suggest that buying stocks in markets with depreciating currencies is the first choice of global investors. Other risks—such as political stability, capital controls and other governmental intervention—can cause large swings in realized returns over certain periods. It does suggest, however, that if it is possible to make money in equities in Argentina and Turkey in both local and U.S. dollar terms, then it certainly is possible to remain confident even when some pundits claim America has lost it exceptionalism or that foreigners may no longer want to own U.S. assets the way they once did. Stocks are still the asset we consider the most resilient and reliable generators of superior long-term real returns. And we fully expect the United States to maintain the conditions for companies to flourish here.

Our Positioning Today

Markets have been very kind for the past four months, gaining 30% from April’s lows. While we remain constructive and fully at target equity exposure generally, we are mindful of seasonal volatility and policy uncertainty. Historically, if something is going to go wrong, it tends to happen in September or October. As a result, we hold modest equity puts as inexpensive insurance.

Looking beyond the near term, we see supportive conditions for equities. November and December have historically been the strongest back-to-back months of the year. A combination of “revolutionary” new technology (AI), a decent economy, and an easing Fed could be a terrific recipe for higher stock prices.

Closing Thoughts

We remain confident in the United States’ global leadership position, cautious on government debt (including that of the United States), and constructive on equities as the most reliable source of long-term real returns. Deficits and dollar risks should not be ignored, but history and evidence suggest that owning businesses—through equities—remains the best way to preserve and grow wealth over time.

As always, we greatly appreciate the opportunity to manage your capital and help you achieve your organization’s goals. We are here to assist in any way possible, so please feel free to reach out to us with any questions or needs.

Your TIFF Investment Team

The materials are being provided for informational purposes only and constitute neither an offer to sell nor a solicitation of an offer to buy securities. These materials also do not constitute an offer or advertisement of TIFF’s investment advisory services or investment, legal or tax advice. Opinions expressed herein are those of TIFF and are not a recommendation to buy or sell any securities.

These materials may contain forward-looking statements relating to future events. In some cases, you can identify forward-looking statements by terminology such as “may,” “will,” “should,” “expect,” “plan,” “intend,” “anticipate,” “believe,” “estimate,” “predict,” “potential,” or “continue,” the negative of such terms or other comparable terminology. Although TIFF believes the expectations reflected in the forward-looking statements are reasonable, future results cannot be guaranteed.